 Amara Maple
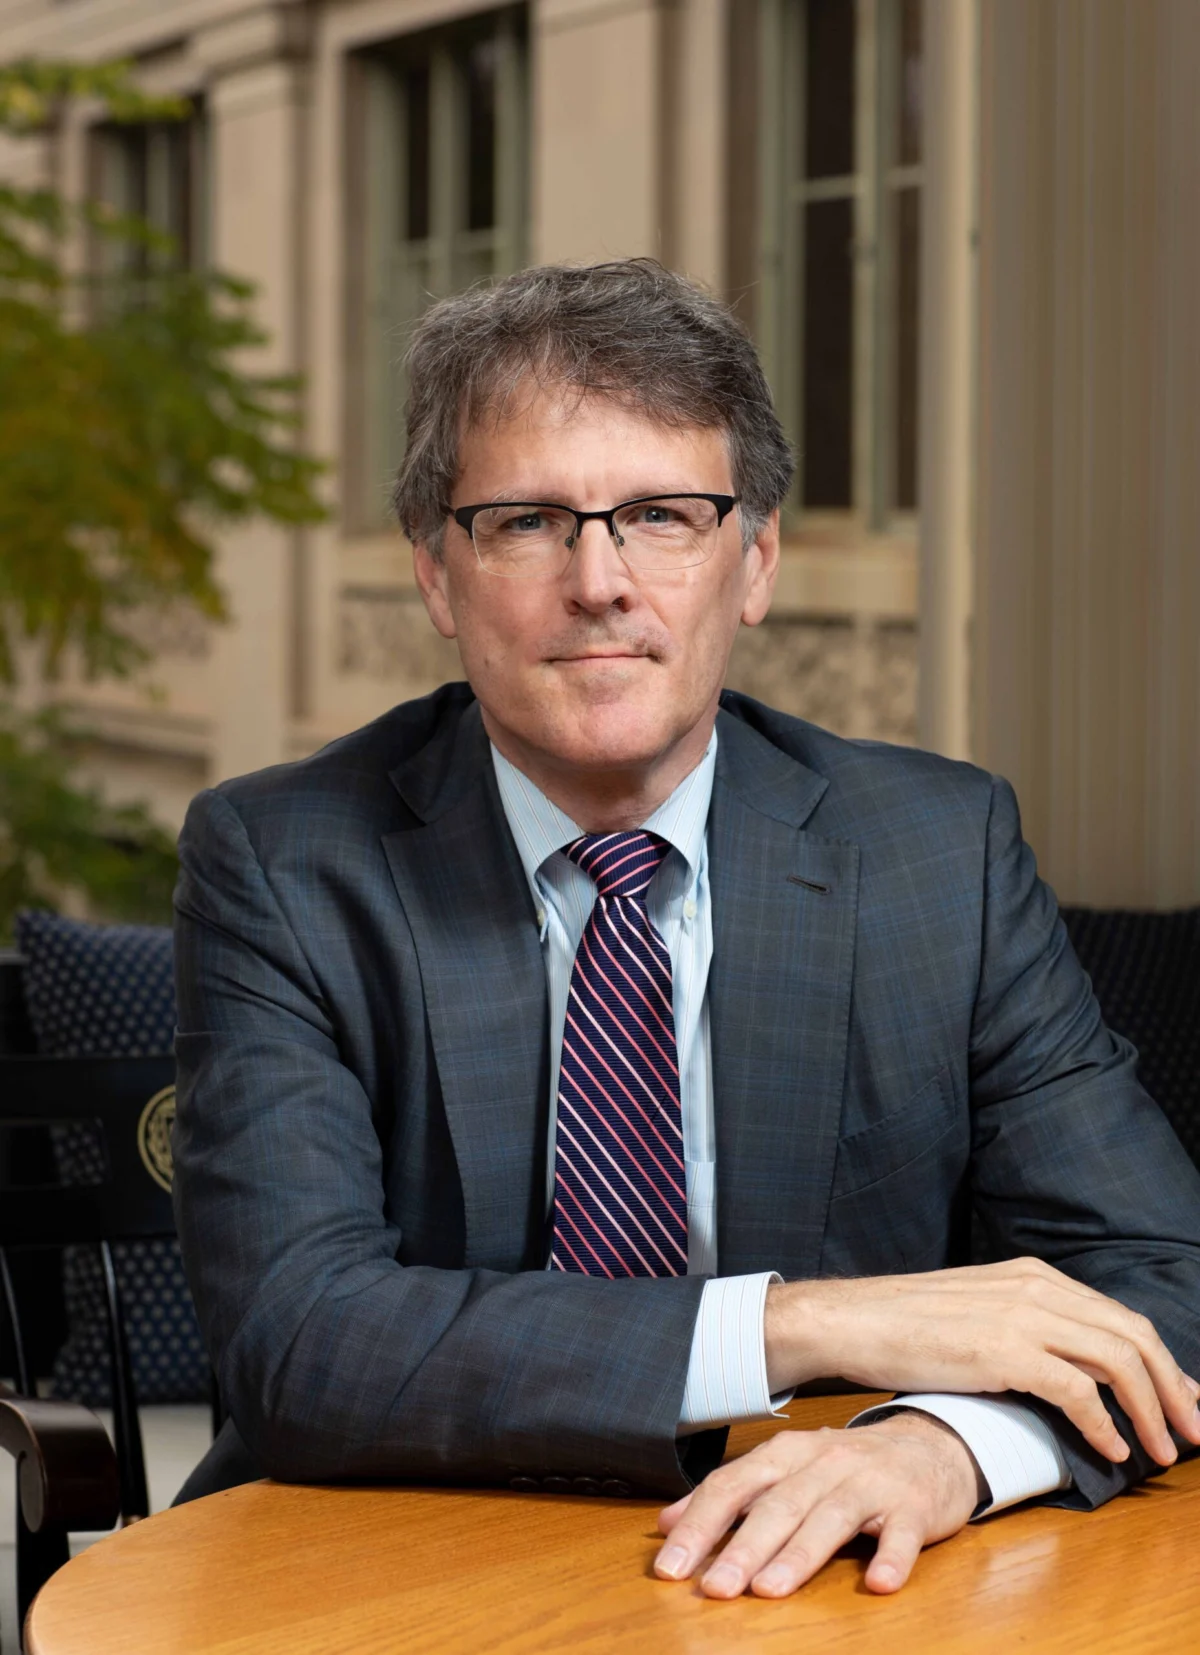
Harvard Law Professor John Coates, a distinguished academic and former top regulator, has emerged as a pivotal figure in the Shadow SEC, an influential collective of securities law professors dedicated to scrutinizing and commenting on the policies of the U.S. Securities and Exchange Commission. In a recent interview with the Corporate Crime Reporter, Professor Coates articulated a sweeping overview of his concerns, categorizing the current SEC’s actions under Chair Atkins into four major areas: unprecedented politicization, dramatic staff cuts impeding core functions, a torrent of regulatory proposals, and the Chair’s engagement in matters beyond the agency’s traditional purview. These criticisms collectively paint a picture of an agency undergoing a profound transformation, raising significant questions about its independence, effectiveness, and the long-term health of the U.S. capital markets.
The Genesis and Mission of the Shadow SEC
The Shadow SEC was formed in response to what its members perceived as a concerted effort by the Trump administration to deregulate capital markets and shift the balance away from investor protection. Comprised of highly respected academics, including Professor Coates, John C. Coffee, Jr. (Columbia Law), James Cox (Duke Law), Merritt Fox (Columbia Law), and Joel Seligman (University of Washington Law), the group provides an independent, expert perspective on SEC policy. Their mission is to serve as a public counterweight, offering detailed analyses and criticisms of proposed rules and enforcement trends that they believe undermine the SEC’s foundational mandate. Over the past year, the Shadow SEC has issued no fewer than eleven critical statements, with four additional ones released since June 2026 alone, underscoring their active engagement and deep concerns regarding the direction of the agency under Chair Atkins. These statements cover a range of critical issues, from disclosure requirements to enforcement priorities, reflecting a comprehensive critique of the administration’s regulatory philosophy.
A Deep Dive into Professor Coates’ Four Categories of Concern
Professor Coates, leveraging his extensive background as a former SEC General Counsel and acting director at the Division of Corporation Finance, as well as a partner at Wachtell, Lipton, Rosen & Katz specializing in financial institutions and M&A, brings unparalleled expertise to his analysis. His insights are further informed by his academic roles at Harvard Law School and Harvard Business School, where he teaches corporate governance, M&A, and finance, and his published work, including "The Problem of Twelve: When a Few Financial Institutions Control Everything" (Columbia Global Reports, 2023).
1. Unprecedented Politicization of the SEC
Coates contends that while political influence on independent agencies like the SEC has always existed, particularly through presidential appointments and congressional oversight, the current administration has escalated this to "a whole order of magnitude more politicized." Historically, the SEC was designed to maintain a degree of independence, with its five commissioners typically balanced across political parties, ensuring no more than three from any single party. This structure was intended to foster bipartisan consensus and shield the agency from direct political manipulation.
However, Coates highlights several alarming indicators of this heightened politicization. Firstly, the absence of any Democratic Commissioners at the SEC since the beginning of the year, with only Republican commissioners appointed to fill three of the five statutory slots, creates an unprecedented partisan imbalance. This effectively silences dissenting voices and eliminates internal debate at the highest levels of the agency. Secondly, Coates points to what he describes as direct "requests, commands, [or] directives" from the White House, which Chair Atkins has overtly embraced. He cites examples such as directives concerning staffing, cooperation with specific market phenomena like the "Elon Musk DOGE operation" (likely referring to the speculative trading surrounding Dogecoin and Musk’s influence), and broader crypto policy. He notes that some of the most recent rulemakings directly mirror publicly announced White House priorities, a level of explicit presidential influence that Coates finds highly unusual and inconsistent with the historical independence of the SEC.
Lastly, the politicization is evident in the dramatic cuts to the agency’s workforce. Coates notes that while political appointees are standard with any new administration, the current cuts have disproportionately affected long-serving civil servants, many of whom are non-partisan career professionals. Their departure, coupled with the influx of new political appointees, significantly amplifies political influence within the agency’s operational layers, potentially compromising its institutional integrity and expert capacity.
2. Dramatic Staff Cuts and Hampered Operational Capacity
The second major category of concern revolves around the severe reduction in SEC staffing, estimated by some reports to be as high as 20%. Coates explains that these cuts were implemented through various means, including buyout offers, early retirement packages, and outright firings. While some turnover is natural with a new administration, the scale of these departures is reportedly "at least double or triple the normal" rate.
The consequences of these cuts are far-reaching and immediately apparent in the agency’s operational efficiency. Coates highlights a slowdown in critical functions such as processing Initial Public Offerings (IPOs) and reviewing registration statements. He argues that the speed and effectiveness with which documents are reviewed and commented upon have demonstrably declined. Drawing on his own experience as a practicing lawyer, Coates emphasizes that the SEC’s review process, while bureaucratic, historically served a vital function: improving disclosure documents, reducing legal risks, and ultimately enhancing investor confidence. He asserts that investor protection is not antithetical to capital formation but rather complementary, as robust oversight makes it easier and safer for investors to commit capital, thereby lowering capital costs for legitimate businesses.
The impact extends to enforcement as well. Although enforcement output typically shows a significant lag due to the time required for investigations, Coates predicts a substantial decline in enforcement actions in the coming years. He posits that a 20% cut in staff will inevitably lead to a corresponding reduction in the agency’s capacity to investigate and prosecute financial misconduct. The protracted onboarding process for federal employees, including security clearances and training, means that even if the agency attempts to rehire, the damage to its investigatory capabilities will persist for an extended period, creating a window for increased illicit activity.
3. A Torrent of Unprecedented Rule Proposals
Coates identifies a third area of concern in the current SEC’s extraordinary pace and scope of rulemaking. He contrasts this with previous administrations, even those perceived as active in rulemaking, such as under Chair Gary Gensler. The current SEC, he notes, is not merely proposing individual rule changes but "bundled proposals," often containing dozens of distinct changes within a single overarching category. These comprehensive revisions span major areas of securities law, including the 1933 Act (governing primary market offerings), the 1934 Act (governing secondary market trading and corporate reporting), the overall capital formation process, the reporting framework, and the assurances companies receive from audit firms.

The sheer volume and breadth of these proposed regulatory changes represent a massive overhaul of the existing framework. Coates suggests that this aggressive rulemaking agenda, coupled with staff reductions, raises questions about the agency’s capacity to adequately analyze, implement, and oversee such extensive changes, potentially leading to unintended consequences and regulatory instability.
4. SEC Chair Atkins Operating "Out of Lane"
Finally, Professor Coates criticizes Chair Atkins for frequently venturing beyond the traditional boundaries of the SEC’s mandate. He cites examples of the Chair offering opinions to the Delaware legislature on how to rewrite state corporate law and publicly encouraging companies to incorporate in Texas, following the lead of figures like Elon Musk. Coates views these actions as indicative of an "unconstrained SEC" that is not primarily focused on its core responsibilities of capital formation and investor protection, but rather on "ticking off political boxes" and engaging in activities that are not traditionally within the agency’s framework. This expansion of influence into areas typically governed by state law or broader economic policy reflects a departure from the agency’s historical role and could blur the lines of federal and state regulatory authority.
Chronology of Shadow SEC Statements (June – August 2026)
The Shadow SEC’s criticisms are not abstract but are grounded in specific policy proposals by the current SEC. Their recent statements highlight these direct challenges:
- June 1, 2026: A critical comment on "The SEC Proposal to Allow Semiannual Reports," arguing against reducing the frequency of corporate financial disclosures, which they believe would diminish transparency and investor information.
- June 26, 2026: A statement addressing "The SEC Proposal to Simplify Filer Status," likely questioning changes that could ease regulatory burdens for certain companies, potentially at the expense of robust oversight.
- June 30, 2026: A forceful critique titled "Shadow SEC Statement No. 10: The SEC’s Proposed Climate Do-Over: Prejudged, Internally Inconsistent, and Partisan," opposing efforts to rescind or weaken climate disclosure rules, which they view as essential for modern investment decisions.
- July 20, 2026: A statement on "The SEC Offering Reform Proposals," analyzing and challenging proposals that aim to streamline capital raising, but which the Shadow SEC fears could reduce investor protections.
- August 11, 2026: "Shadow SEC Statement No. 12: The SEC’s Retreat from Enforcement and the Special Case of Mandatory Arbitration Clauses," which explicitly addresses the decline in enforcement activity and raises concerns about policies that limit investor recourse, such as mandatory arbitration. This statement, issued shortly after Coates’ interview, underscores the group’s ongoing focus on enforcement issues. Earlier, the Shadow SEC had also issued a statement (number three) titled "The SEC’s FCPA Books and Records Provision Must be Vigorously Enforced," signaling an early concern about enforcement priorities.
Broader Implications and Market Forecast
The cumulative effect of these changes, according to Professor Coates, is a predictable and alarming shift in market dynamics. He warns that a dramatic fall in enforcement, coupled with deregulation, will inevitably "increase fraud" and alter the calculus for market participants, favoring "more lawbreaking." While this might initially appear to stimulate capital formation by enabling unscrupulous actors to attract investment through deceit, Coates predicts that such fraudulent activities will eventually be exposed, leading to a loss of investor trust, increased capital costs, and a long-term decline in legitimate capital formation.
He draws stark historical parallels, suggesting that the current trajectory could lead to "something similar to the lead up to Enron or the pre-2008 lead up," where concentrated series of frauds eventually precipitate market collapses. The resulting public outrage, as seen with the unanimous passage of the Sarbanes-Oxley Act after Enron, would then force a return to robust regulation. Coates believes that while the average American may not immediately grasp the nuances of semiannual reports versus quarterly reports, they will care profoundly when these policies hit their "pocketbooks" through market instability and personal financial losses. He acknowledges that Chair Atkins may genuinely believe his proposals are not "a big deal," but argues that the decimation of staff removes crucial internal expertise and dissenting voices that could warn of the true consequences.
The Silence of SEC Alumni and Large Law Firms
A pertinent question arises regarding the relative silence of former SEC officials and large corporate law firms, many of whom comprise a powerful legal community that often engages with SEC policy. Professor Coates acknowledges the complexity of this issue. While he, as an academic, enjoys the freedom to speak out, lawyers at large firms face significant constraints. Their primary obligation is to their clients, and taking public policy stances can complicate client relations or even expose firms to political blowback. Coates points to instances during the "very first week of the second Trump administration" where there were "attacks on the law firms" that have been legally challenged, suggesting a chilling effect. He posits that major firms are likely prioritizing their own defense against such political pressures, followed by broader rule of law issues, before addressing specific SEC policies.
Why Not a CFPB-Style Shutdown?
Coates offers an insightful explanation as to why the SEC, unlike the Consumer Financial Protection Bureau (CFPB) under previous administrations, has not faced attempts at an outright shutdown. He argues that even Chair Atkins and the majority of Republicans understand that "capital formation depends on investor protection." Shutting down the SEC entirely, he believes, would trigger an immediate and catastrophic loss of investor confidence, severely impacting the capitalist system that Republicans largely champion. Investor protection, therefore, is recognized as a "core capitalist need."
This distinguishes the SEC from agencies like the CFPB, which often face more fundamental ideological opposition from those who view its consumer protection mandate as overreach. Coates suggests that while there may be legitimate public policy debates within the SEC regarding the optimal balance between investor protection and capital formation, some of the current administration’s actions are "purely political in nature," aimed at "placating his boss and checking off certain boxes to perform in a political way" rather than engaging in a reasoned discussion about market efficiency or investor welfare.
Conclusion
Professor John Coates and the Shadow SEC stand as a critical independent voice in a rapidly evolving regulatory landscape. Their detailed and consistent critiques underscore a profound concern that the current SEC’s trajectory—marked by politicization, operational degradation, rapid deregulation, and an expanded scope of influence—risks undermining the very foundations of investor trust and market stability that the agency was established to protect. As the capital markets navigate these shifts, the Shadow SEC’s vigilance and expert analysis offer crucial insights into the potential long-term consequences for investors, corporations, and the broader economy. The coming years, Coates warns, may reveal whether this era of deregulation leads to a resurgence of financial scandals and a subsequent demand for renewed regulatory oversight, echoing historical cycles of market exuberance, collapse, and reform.

 Yuyun Lusiyani
 Ana Megawati
 Joko Widodo
 Eva Lovia
 Jia Lissa
 Pevita Pearce
