 Amara Maple
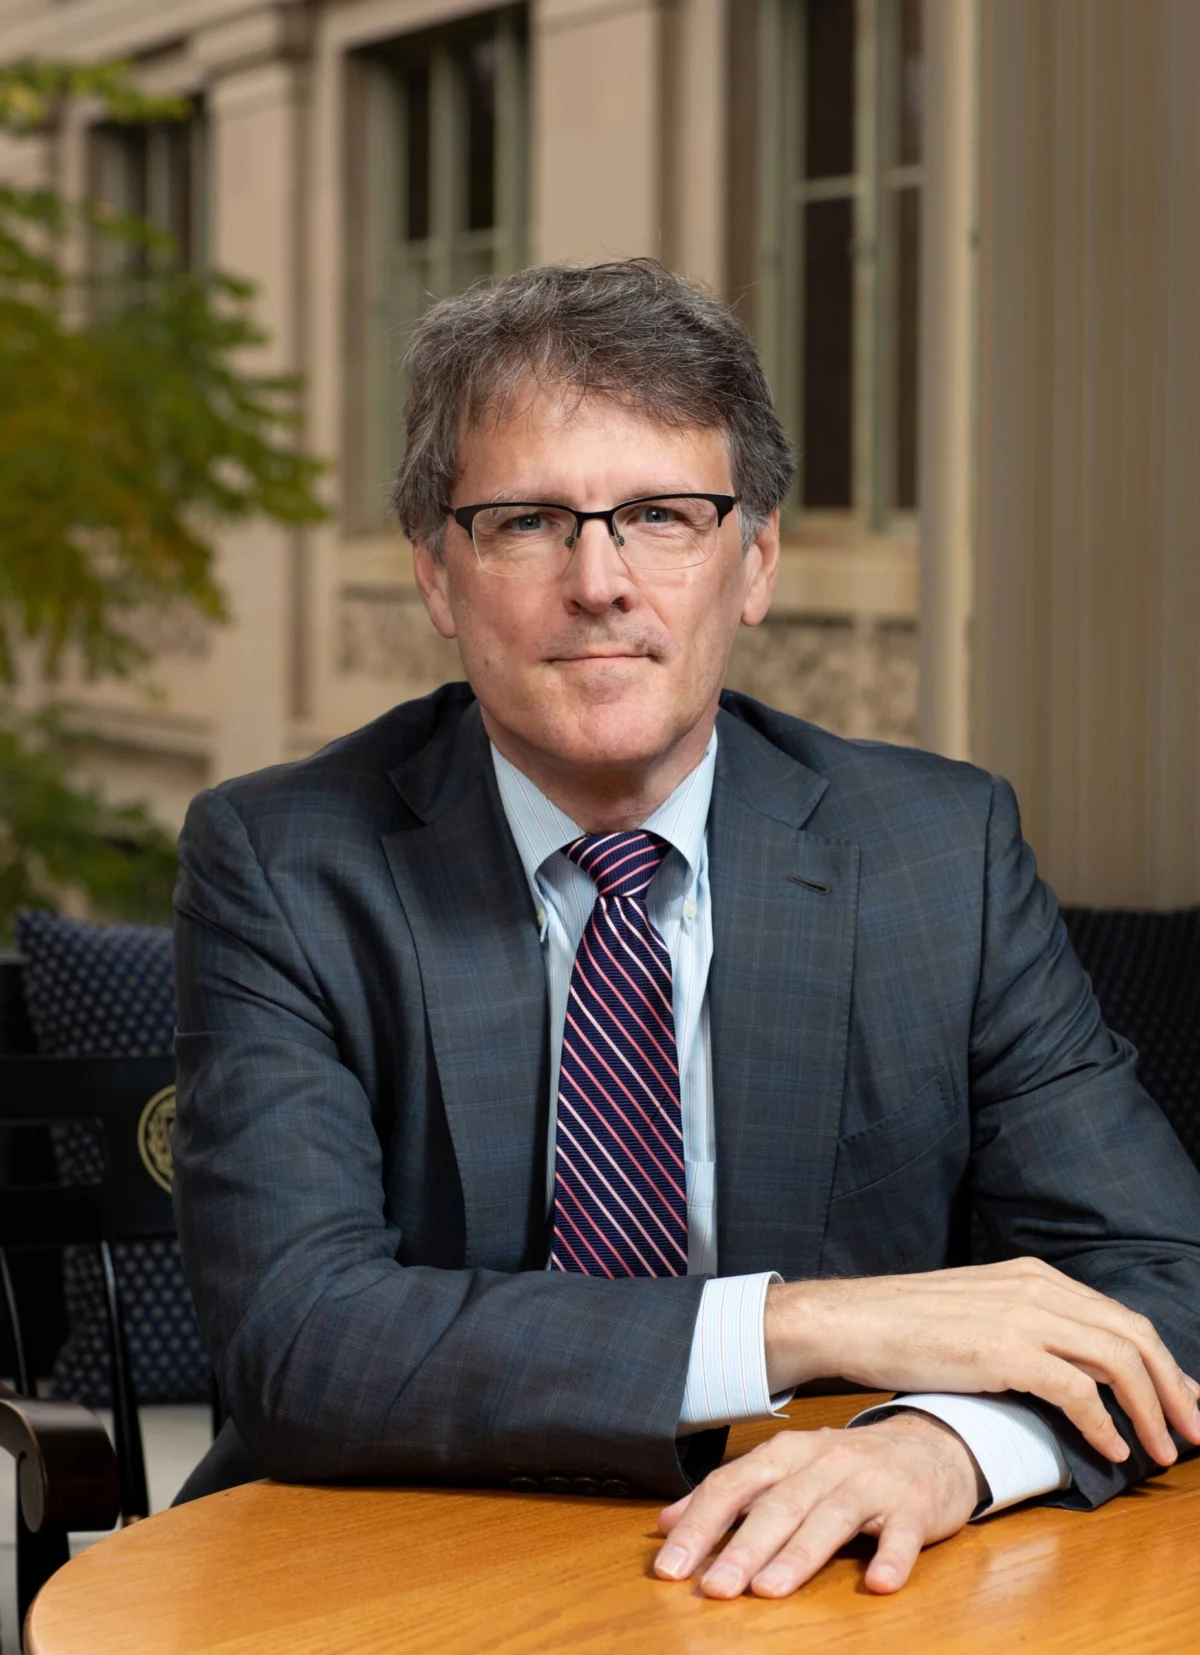
Harvard Law Professor John Coates, a distinguished figure in corporate governance and securities law, has emerged as a prominent critic of the current direction of the U.S. Securities and Exchange Commission (SEC). As a founding member of the Shadow SEC, a collective of leading securities law academics, Coates and his colleagues have voiced significant concerns regarding what they describe as an unprecedented politicization, aggressive deregulation, and operational undermining of the regulatory body responsible for protecting investors and maintaining market integrity. Their collective critique, articulated through a series of public statements and expert interviews, suggests a trajectory that could significantly increase market instability and investor risk.
The Genesis of the Shadow SEC and Its Mission
The Shadow SEC was formed as a response to perceived shifts in the SEC’s traditional role and priorities, particularly under the Trump administration. Composed of eminent securities law professors including Coates, John C. Coffee, Jr. (Columbia Law), James Cox (Duke Law), Merritt Fox (Columbia Law), and Joel Seligman (University of Washington Law), the group acts as an academic watchdog, offering expert analysis and critiques of proposed SEC policies and enforcement trends. Their mission is rooted in the belief that robust, independent regulation is essential for healthy capital markets, a principle they argue is being eroded.
Professor Coates himself brings a wealth of experience to this critical oversight role. Prior to his tenure at Harvard Law School and Harvard Business School, where he teaches corporate governance, M&A, and finance, Coates served as general counsel of the SEC and acting director at the Division of Corporation Finance. His private sector experience includes a partnership at Wachtell, Lipton, Rosen & Katz, specializing in financial institutions and M&A. He has advised various government bodies, including the U.S. Department of Justice and the Department of Treasury, and chaired the Investor-as-Owner Subcommittee of the Investor Advisory Committee of the SEC. His insights are further informed by his recent book, The Problem of Twelve: When a Few Financial Institutions Control Everything (Columbia Global Reports, 2023), which explores systemic risks in financial markets.
A Litany of Concerns: Four Categories of Critique
In a recent interview with Corporate Crime Reporter, Professor Coates outlined the Shadow SEC’s criticisms across four major categories, painting a stark picture of an agency veering away from its foundational principles.
1. Unprecedented Politicization of the SEC
Coates highlighted a significant and troubling increase in the politicization of the SEC, exceeding historical norms. While acknowledging that political influence from the President and Congress has always existed, he argued that the current situation represents "a whole order of magnitude more politicized."
Traditionally, the SEC, as an independent agency, was designed to have a degree of insulation from direct political pressures. Its enabling statute mandates that no more than three of its five commissioners can belong to one political party, a measure intended to foster bipartisan consensus and prevent partisan capture. However, Coates noted that since the beginning of 2026, the SEC has operated without any Democratic Commissioners, with the two slots left unfilled, effectively consolidating control within one party.
Further evidence of politicization, according to Coates, includes Chair Atkins’ overt responsiveness to White House directives. He cited instances such as "commands about staffing," cooperation with the "Elon Musk DOGE operation," and specific instructions regarding crypto regulation. Such direct engagement from the White House in shaping the SEC’s agenda is "unusual," Coates contended, noting that previous administrations rarely attempted to dictate the independent agency’s priorities so explicitly and publicly. The Chair’s apparent embrace of these directives, whether through agreement or acquiescence, marks a significant departure from the traditional independence expected of the SEC.
This politicization extends to the agency’s internal structure. Coates described "dramatic cuts" to the SEC’s long-serving civil servants, many of whom previously maintained a non-partisan approach to their work. While political appointees are customary with each new administration, the widespread dismissal or incentivized departure of career staff, replaced by new political appointees, significantly amplifies political influence within the agency, potentially undermining institutional knowledge and regulatory consistency.
2. Crippling Staffing Cuts and Operational Deterioration
The second major area of concern stems directly from the reduction in SEC staff, which Coates estimates to be around 20%. These cuts, facilitated through buyouts, early retirement packages, and firings, have had a tangible negative impact on the agency’s core functions.
Coates explained that a significant reduction in personnel inevitably hampers the SEC’s ability to process essential documents efficiently. This includes reviewing Initial Public Offerings (IPOs) and registration statements, critical components of the capital formation process. He noted a decline in the speed and effectiveness of document review and feedback, which in turn slows down companies’ ability to access public markets. While acknowledging that some complex cases, like SpaceX, naturally require longer review times, the overall trend points to a systemic slowdown.
Critically, Coates challenged the simplistic notion that investor protection impedes capital raising. Drawing on his past experience at Wachtell, Lipton, Rosen & Katz, he asserted that SEC staff comments invariably "improved the documents," reducing the risk of future legal disputes and enhancing investor confidence. This investor protection, he argued, is "complementary to the capital raising process," as it fosters a safer and more transparent market, ultimately making it easier for non-fraudulent companies to attract capital at lower costs. A diminished staff, therefore, leads to less effective and slower regulatory oversight, creating a less trustworthy environment for investment.
The impact is also projected to extend significantly to enforcement. While enforcement actions typically have a "big lag" before becoming public due to the investigative process, Coates predicted a "dramatically fallen off" enforcement output in the coming years. He argued that it is "common sense" that such severe staff cuts would weaken the agency’s ability to investigate and prosecute securities violations. Even if rehiring were to occur, the lengthy onboarding process for federal employees, including security clearances, means a substantial delay in restoring full operational capacity, leaving a significant void in regulatory vigilance.
3. An Accelerated and Bundled Rulemaking Agenda
The current SEC has embarked on an unprecedentedly rapid and extensive rulemaking agenda. Coates, who worked under former SEC Chair Gary Gensler, noted that while Gensler’s tenure also saw numerous rule proposals, the present pace is "significantly faster."
The current approach involves "bundled proposals," where single regulatory initiatives encompass dozens of distinct rule changes. This leads to a "massive amount of proposed regulatory changes on the table" across all major areas of the SEC’s purview, including the Securities Act of 1933 (governing capital formation), the Securities Exchange Act of 1934 (governing reporting frameworks), and audit firm assurances. These "huge and pretty dramatic rule making proposals" are designed to significantly alter the regulatory landscape, often in ways that reduce compliance burdens for corporations, aligning with the broader deregulation push of the administration. Critics argue that such a rapid pace and bundling can lead to insufficient public review and potentially less robust, well-considered regulations.

Chronology of Shadow SEC Statements (June-August 2026)
The Shadow SEC’s criticisms are not merely theoretical; they are grounded in concrete responses to specific SEC proposals. Over the past year, the group has issued eleven statements, with four new ones released since June 2026, directly addressing the Chair Atkins-led SEC’s policy shifts.
- June 1, 2026: The SEC Proposal to Allow Semiannual Reports. The Shadow SEC voiced concerns that shifting from quarterly to semiannual reporting would reduce the frequency of material information available to investors, potentially hindering informed decision-making and increasing information asymmetry.
- June 26, 2026: The SEC Proposal to Simplify Filer Status. This proposal aimed to streamline requirements for certain companies. The Shadow SEC likely argued that simplifying filer status without adequate safeguards could exempt companies from crucial disclosure requirements, particularly those designed to protect smaller investors.
- June 30, 2026: The SEC Proposal to Rescind Climate Disclosure Rules. This statement, titled "The SEC’s Proposed Climate Do-Over: Prejudged, Internally Inconsistent, and Partisan," was particularly strong. It criticized the rescission of rules designed to mandate disclosure of climate-related risks, arguing that such information is material to investors and that the reversal was politically motivated and lacked a sound analytical basis.
- July 20, 2026: The SEC Offering Reform Proposals. These proposals aimed to simplify and expedite the capital raising process. The Shadow SEC likely cautioned that while reform can be beneficial, proposals that overly prioritize speed over investor protection could lead to increased risks for those participating in public offerings.
- August 11, 2026: The SEC’s Retreat from Enforcement. This, the twelfth statement, published just after the interview, specifically addressed the broader decline in enforcement actions and the controversial issue of mandatory arbitration clauses, signaling a comprehensive weakening of investor safeguards.
4. Chair Atkins’ Expanded and Unconstrained Scope
The fourth category of critique centers on Chair Atkins’ tendency to offer opinions and directives on subjects traditionally considered "out of the SEC’s lane." Coates cited instances where Atkins intervened in state-level corporate law debates, such as advising the Delaware legislature on rewriting corporate law or encouraging companies to incorporate in Texas, following the lead of figures like Elon Musk.
These actions, Coates argued, demonstrate "a much more unconstrained SEC across the board," one that is "not playing traditional roles, not mostly focused on capital formation, mostly trying to tick off political boxes." This expansion beyond the SEC’s statutory mandate is seen as further evidence of politicization, where the agency’s leadership is using its platform to advance broader political or ideological agendas rather than adhering strictly to its mission of investor protection and market regulation. This marks a significant departure from SEC behavior "at least since the 1970s."
Broader Impact and Implications: A Looming Threat of Fraud
The cumulative effect of politicization, staffing cuts, accelerated deregulation, and an expanded, unconstrained scope, according to Coates, is deeply concerning for the integrity and stability of U.S. capital markets. He warned of a predictable increase in fraud.
"It will increase fraud," Coates stated unequivocally. "It will shift the calculus that people engage in every day between complying with the law and not complying with the law. It will shift toward more lawbreaking." While this might temporarily boost investment and capital formation by allowing companies to "cheat and lie," Coates predicts that such fraudulent activities will inevitably be discovered. This, in turn, will erode investor confidence, drive up the cost of capital, and ultimately lead to a decline in legitimate capital formation.
Coates drew parallels to historical periods of lax regulation, such as the lead-up to the Enron scandal and the 2008 financial crisis. He suggested that the current environment could similarly produce a "predictable surge in scandals" that will eventually impact "the market as a whole," not just individual companies or investors. The public, he believes, will eventually care "at the moment it hits their pocketbooks," as evidenced by the unanimous passage of the Sarbanes-Oxley Act after public outrage over 401k collapses following the Enron debacle.
The Silence of SEC Alums and Law Firms
A pertinent question arises regarding the lack of vocal opposition from former SEC officials now working in major corporate law firms. These individuals, many of whom served in enforcement roles, possess deep institutional knowledge and a vested interest in the agency’s effectiveness.
Coates acknowledged the complexity of their position. While he, as an academic, enjoys greater freedom to take public policy stances, lawyers in large firms face potential conflicts of interest and the need to prioritize client relations. Furthermore, he noted that the current administration’s "illegal and unconstitutional attacks on law firms" during its first week in office—attacks that have been challenged in court—have likely made larger firms hesitant to engage in public criticism. Their primary focus, Coates inferred, is defending the firms themselves and the broader rule of law, with specific SEC policies taking a backseat. He suggested that any public resistance from the legal community might first emerge from smaller firms.
Distinguishing the SEC’s Fate from the CFPB’s
While the SEC is facing significant undermining, it has not been "effectively shut down" in the same manner as the Consumer Financial Protection Bureau (CFPB) under previous administrations. Coates attributed this differential treatment to a fundamental recognition among even some Republicans that "capital formation depends on investor protection."
"Investor protection is a core capitalist need," Coates explained. Unlike the CFPB, whose mission was more directly linked to consumer advocacy, the SEC’s role in ensuring fair and transparent markets is seen as crucial for the functioning of capitalism itself. Shutting down the SEC entirely, he argued, would cause investors to "stop investing at the level they are now," an outcome likely deemed unacceptable by those who still believe in a functioning capitalist system. While Chair Atkins may hold differing views on the precise balance between investor protection and capital formation—a "legitimate public policy debate"—Coates reiterated that many of his actions are "purely political in nature," aimed at "placating his boss and checking off certain boxes."
Internal Dynamics and the Absence of Pushback
Coates further elaborated on the internal consequences of the staff cuts and politicization. The decimation of staff leads to a loss of "skilled people who can warn about what the consequences are of what you are doing." Moreover, the absence of Democratic commissioners and their dedicated staff removes a vital source of "normal push back" and dissenting opinions. "That’s twenty smart, dedicated people who would have told you what you are doing is wrong in fifteen different ways," he lamented. The current environment, devoid of internal debate and critical analysis, creates a fertile ground for unintended negative consequences and policies that may not be fully scrutinized before implementation.
Conclusion: A Critical Juncture for Market Integrity
The Shadow SEC, led by figures like Professor John Coates, presents a compelling and detailed critique of the current direction of the U.S. Securities and Exchange Commission. Their analysis points to a worrying trend of politicization, operational degradation, and regulatory rollback that could have profound and detrimental effects on market integrity, investor confidence, and ultimately, the long-term health of the U.S. capital markets. The warnings from these distinguished academics suggest that while the immediate impacts may seem incremental, the cumulative effect risks creating an environment ripe for fraud and systemic instability, potentially leading to future crises that will undoubtedly capture public attention and demand political reckoning. The ongoing debate between deregulation and investor protection, amplified by these criticisms, marks a critical juncture for the future of financial oversight in the United States.

 Yuyun Lusiyani
 Joko Widodo
 Eva Lovia
 Jia Lissa
 Pevita Pearce
 admin
